
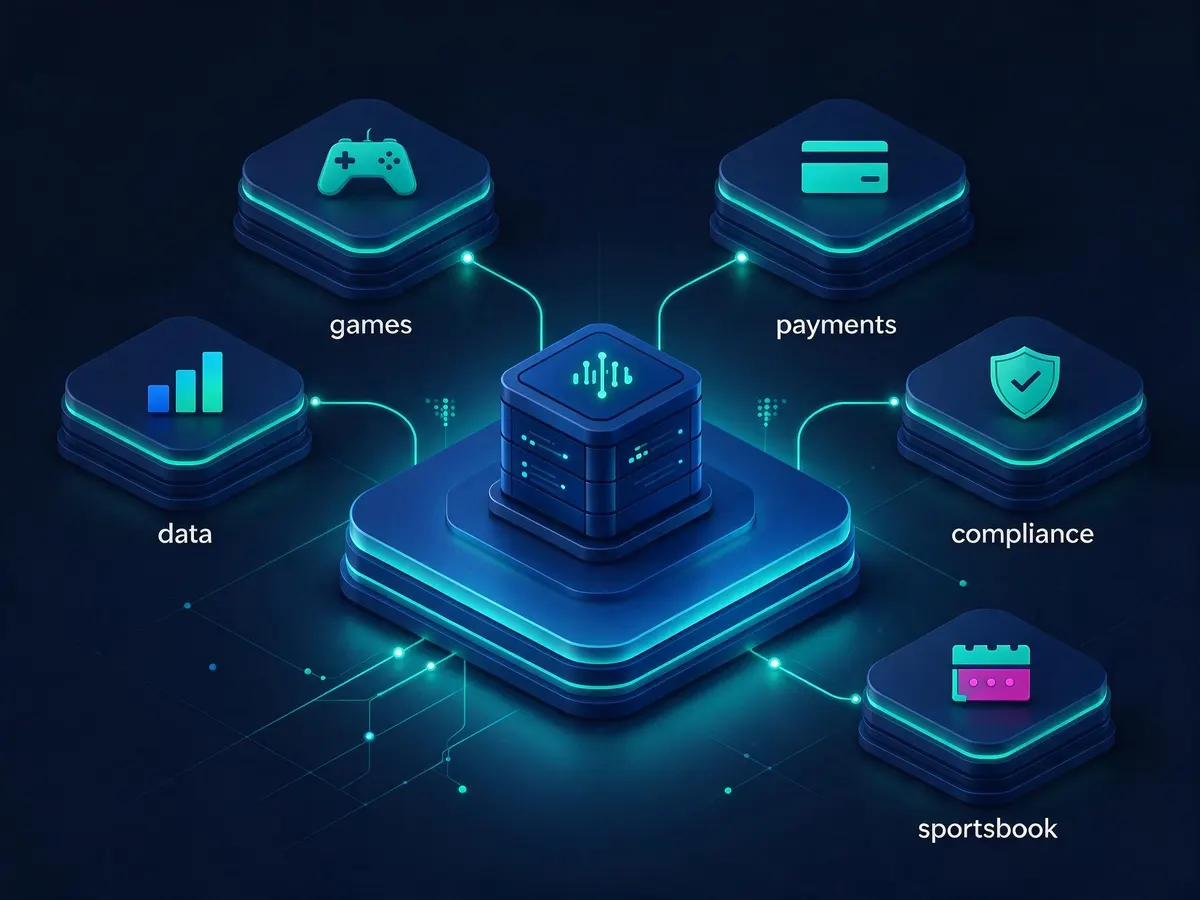
Casino game aggregation is expanding beyond game libraries into payments, data and operational services. What Alea's broader model means for operators.
The short version: the game library is no longer the product
How many separate vendor contracts does it take to run a mid-sized online casino? Count them honestly and the number is usually embarrassing: one aggregator for content, two or three payment providers per market, a CRM, a bonus engine, a reporting layer, a KYC vendor, maybe a jackpot supplier on top. That sprawl is the commercial pressure now reshaping casino game aggregation.
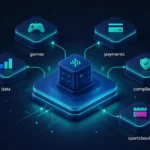
The direction of travel is straightforward. Aggregators that spent a decade selling access to thousands of games are moving into payments, data, jackpots and even sportsbook, because a single content API is no longer a difference worth paying for. Alea, presenting at SBC Summit Lisbon and SiGMA Rome, is one of the clearer examples: founder Alexandre Tomic’s position, in his own words, is that “aggregation has to become broader than games.”
For operators, this is less a technology story than a procurement one. The question is shifting from “how many studios can you give me?” to “how much of my stack are you willing to own, and what happens when I want it back?”
What casino game aggregation traditionally covers
Classic aggregation solves one specific problem: game integration at scale. Instead of negotiating, certifying and maintaining a direct connection to every studio, an operator integrates once with the aggregator and inherits the catalogue.
In practice, that bundle has looked like this:
- One API for game launch, session handling, bet and win callbacks, and round history.
- Single-wallet integration, so the player’s balance stays with the operator rather than fragmenting across providers.
- Content management tools: lobby categories, game availability by jurisdiction, RTP variant selection where studios offer it, and demo mode.
- Commercial consolidation: one contract, one revenue-share invoice, one set of reconciliation reports instead of forty.
- Certification support for the markets where each game is approved.
That is genuinely useful work, and it is also close to commoditised. Most serious aggregators now list broadly similar studio rosters, and the big names appear in every catalogue. The limitations are familiar: the aggregator stops at the lobby edge. It tells you which games were played, not why the player churned, whether the deposit attempt failed, or how the bonus cost compared with the payment fees in that market. Operators end up stitching those answers together from four dashboards, usually in a spreadsheet, usually a week late.
Alea’s case for “broader aggregation”
Tomic’s argument, made in an interview around SBC Summit Lisbon, is that a content aggregator cannot keep selling content alone. Alea is extending its model into payments, an expanded jackpot offering, and a sportsbook vertical launched with FIRST.bet, which the company is now taking to other operators.
The market logic behind that is visible in his comments on Brazil, which remains one of Alea’s priority markets despite higher taxes, higher marketing costs and heavier compliance requirements. His warning there is worth repeating for anyone building a multi-market roadmap: operators cannot transplant European playbooks into Brazil, where player behaviour and market trends move quickly. A regulated market with thin margins and fast-changing behaviour punishes slow stacks. If a promotion, a payment route and a reporting change each require a different vendor ticket, the operator is reacting in weeks while the market moves in days.
That is the real case for broader aggregation: not “more products from one supplier” as a sales pitch, but fewer integration seams between the things an operator has to change under pressure.
Payments move inside the platform
Payments are the obvious second module, because in a regulated market they fail more often and cost more than content does. An iGaming platform that already holds the wallet is structurally well placed to route transactions through it.
What “payments in aggregation” usually means technically:
- Orchestration rather than processing. The platform connects multiple local providers and routes each attempt by method, amount, device and success rate, with automatic failover when one acquirer degrades.
- Local method coverage. Pix in Brazil, UPI and local bank rails in India, vouchers and mobile money elsewhere. Method mix, not card support, decides conversion in most emerging markets.
- Cashier logic in one place: deposit limits, minimum and maximum amounts, duplicate-attempt handling, and withdrawal queues tied to the same account record as the gameplay.
- Financial compliance tooling: KYC and AML checks triggered by thresholds, source-of-funds flags, transaction monitoring, and audit-ready records for the regulator.
- Reconciliation that matches gameplay liability to settled cash without a manual export.
The unglamorous detail that matters most in diligence: who is the merchant of record, who holds the provider contracts, and whether the operator can see raw approval rates per route. An orchestration layer that hides which acquirer declined a deposit is a reporting product, not a payments product.
Data analytics and player intelligence
Once games and payments share a platform, the data becomes worth something. A content-only aggregator can report rounds, stakes and margin by game. A broader platform can join that to deposits, declines, bonus cost and session behaviour in the same schema, which is where useful operator tools start.
Typical capabilities being bundled now include cohort and retention reporting, segmentation by value and behaviour, game performance against bonus spend, churn indicators, and dashboards that give the commercial team numbers without a BI request. Some platforms layer recommendation engines on top, surfacing titles based on a player’s volatility preference and session length rather than a flat “popular games” row.
Two caveats deserve stating plainly. First, player-level data is regulated personal data, so processing roles, retention periods and cross-border transfers belong in the contract, not in a feature list. Second, the same behavioural signals that drive marketing also drive responsible gambling: rising deposit frequency, chasing patterns, long overnight sessions. Platforms that model one and ignore the other are only half built, and regulators in newer markets are increasingly explicit about that.
Operational services: compliance, CRM, jackpots, support
The third layer is everything that used to sit in the “we’ll buy that separately” column.
Compliance management is the heaviest piece: jurisdiction-level game availability, licence-specific reality checks and session reminders, self-exclusion registry connections, regulatory reporting formats, and tax or levy calculations that differ by market. Marketing automation and CRM follow, because bonus engines, free-spin campaigns and lifecycle messaging only work well when they read the same event stream as the games and the cashier. Add network jackpots, which need shared liquidity across operators to produce prizes worth advertising, and support tooling that lets an agent see a disputed round and the deposit behind it on one screen.
Below is how the two models compare in scope, and what each layer actually forces an operator to ask.
| Layer | Classic game aggregation | Broader aggregation model | Question for the vendor |
|---|---|---|---|
| Content | One API, multi-studio catalogue, lobby tools | Same, plus jackpots and sportsbook in one wallet | Which titles are certified for my licences? |
| Payments | Out of scope | Routing, local methods, cashier rules, failover | Who is merchant of record, and do I see per-route approval rates? |
| Data | Game and GGR reporting | Player-level analytics, retention, bonus cost vs revenue | Can I export raw event data on exit? |
| Compliance | Game availability by market | KYC/AML triggers, RG tooling, regulatory reporting | Which obligations stay mine as licence holder? |
| Engagement | Bonus support via operator platform | CRM, campaign automation, recommendations | Does the bonus engine respect game weighting correctly? |
What it changes for operators, and for players
For the operator, the gain is mostly measured in removed friction. Fewer integrations means fewer failure points, fewer reconciliation mismatches, and a shorter path from “this market needs a different promotion” to the promotion being live. Revenue optimisation becomes a legitimate exercise rather than guesswork, because bonus spend, payment fees and game margin finally sit in the same report. Launching a new jurisdiction looks more like configuration than a project.
For the player, the effect is quieter and arguably more valuable. One balance across casino, live tables and sportsbook. A cashier that offers the local method that actually works and retries intelligently when it does not. Game recommendations that reflect what they play instead of what the commercial team is pushing this week. Support that can see the round and the transaction together. Nobody ever praised an operator for its orchestration layer, but they notice when a withdrawal clears without three emails.
The trade-off is concentration. Putting content, payments, data and compliance tooling behind one vendor creates dependency, and dependency gets expensive at renewal. Before signing, pin down data portability and export formats, uptime and incident history for the payment layer specifically, whether modules can be taken individually or only as a bundle, which compliance duties remain with the licence holder, and how commercial terms stack once revenue share, payment fees and jackpot contributions are added together. Also test the exit: an aggregator that cannot describe a migration path has answered the question.
Operators carrying a licence also carry the player protection obligations that come with it. Deposit and loss limits, cool-off and self-exclusion, and reality checks should be verifiable in whichever platform ends up holding the player record, not assumed because a vendor listed them on a slide.
FAQ
What is broader aggregation?
Broader aggregation means an aggregator supplying more than games through its integration: payments routing, player data and analytics, compliance tooling, jackpots, CRM and in some cases a sportsbook, all tied to the same wallet and API. Tomic’s framing at Alea is that aggregation “has to become broader than games” because content alone no longer differentiates suppliers.
How does casino aggregation work?
The operator integrates once with the aggregator’s API. The aggregator holds the studio relationships and relays game launches, bets, wins and round history between the games and the operator’s wallet, while handling per-market certification and consolidating reporting and billing. The operator keeps the player balance and, usually, the licence obligations.
Why expand beyond games?
Because margins in newly regulated markets are tight and catalogues look alike. Alea points to Brazil, where higher taxes, higher marketing costs and stricter compliance requirements squeeze operators and player behaviour shifts fast. In that environment, value comes from faster payments, better data and quicker configuration changes rather than from another hundred slot titles.
Gambling involves risk and every game carries a built-in house edge. Operators and suppliers should treat player protection tooling as part of the product, not an add-on.